

Lesa Miller, Broker | REALTOR®
Lesa Miller Real Estate
RE/MAX Acclaimed Properties
Serving Bloomington, Bedford and the Surrounding Indiana Communities
📞 (812) 360-3863
📧 [email protected]
🌐 https://LesaMillerRealEstate.com
Welcome To Bloomington Seller's Course
Here's What You Need to Know About Selling a Home in BLOOMINGTON...
WELCOME TO BLOOMINGTON
SELLER'S COURSE
Here's What You Need to Know About Selling a Home in BLOOMINGTON...
|
|
Seller's Course
Module 1: Choosing Your Agent
Module 2: Marketing in Today's World
Module 3: Sellers WAIT Before You Pack Those Bags
Module 4: Compensation Commissions
Module 5: Savvy Negotiations
Module 6: The Importance of Communications
Module 7: Savvy Sellers Goals and Priorities
Module 8: Getting Clarity
Module 9: How to Prepare for a Great Sale
Module 10: Do's and Don'ts When Selling Your Home
Exclusive Market Updates
We know selling a property can be stressful and overwhelming! That’s why we got you covered. With the right team by your side, we will guide and navigate you through the selling process to help you make informative decisions and get the best terms possible on your sale!
Our exclusive market updates will help you stay ahead of the curve with our up to minute market updates. From the latest listings, price trends and days on market, we ensure you will have all the information you need to make informed decisions on your sale. BLOOMINGTON real estate landscape is dynamic, and with our expert analysis you will always be well informed and in the know.
market Updates
Considering Selling?
Selling a home can be an exciting but also challenging experience. If you're planning to sell your BLOOMINGTON home, it's important to be prepared and aware of what to expect throughout the process. This short guide is designed to provide savvy sellers like you with valuable insights and tips to navigate the sale of your Bloomington property successfully.
DOWNLOAD TO ACCESS:
The Complete Guide to Selling A Home
Spring is here!
The Spring Real Estate Market is thriving, and we are seeing a significant increase in demand for homes in Voorhees, especially from millennials.
In fact, the current absorption rate in our area is only 3 months, which means that if no more homes come on the market, we will only be able to sustain the current demand for up to 3 months.
This is great news for anyone considering selling their home, as the high demand can lead to a boost in your bottom line.
If you are thinking about selling your home, now is the perfect time to do so. To get started, it's essential to focus on your curb appeal, which can significantly impact the value of your property. That's why we've put together a helpful checklist to help you get started.
Friendly reminder: Before you make a repair, be sure to check with a real estate agent to make sure it is worth your return on investment. Feel free to Book A Call with me if you have any questions or want a free consultation!
Are you a little behind on your spring cleaning? Grab a copy of the Ultimate Spring Cleaning Checklist that was featured last month.
Preparing for a possible move this summer? Click below to check out our moving checklist to get your whole house ready for the next home!
Want to know what is happening throughout BLOOMINGTON Now?
Click below for a full live schedule of local events around town!
BLOOMINGTON STATS & LOCAL INFO
Click Here for the Census Data.
Click Here for the BLOOMINGTON Report Card from Niche.
DOWNLOAD TO ACCESS:
30 Day Plan to Prepare Your Home for Sale
DOWNLOAD TO ACCESS:
The Complete Guide to Selling A Home
market Updates
buying new construction? buyer beware
Local market update
NAR's Commission Settlement:
Understanding Buyer's Agent Compensation
National Market Update
Buyer Tips
Community Videos
3 best sandwich Shops
Best Burrito in Brentwood
Best Hot Dogs in Brentwood
MJ's Cafe in brentwood
Welcome To The Virtual Seller Course For
BLOOMINGTON
If you are a homeowner either thinking about selling or already made the decision to sell, but still have questions or concerns regarding the process, price or anything else, you are in the right place.
This free seller course will give you the exact step by step blueprint on everything you need and guide you through the selling process, so you can make the best decision on selling your home for top dollar.
You will learn about marketing your home, timelines, pricing, negotiations and so much more.
Take a look around and let us show how we can help you.
LESA MILLER | Realtor & Broker
LESA MILLER REAL ESTATE
Lic# RB14023899
Welcome To The Virtual Seller Seminar Library
Learn the latest and most up to date marketing and sales tactics
to sell your home for top dollar.
The Pre-Market Test
"Will your home pass the test before going to market?"
First impressions matter—curb appeal, cleanliness, and staging can greatly impact your home's value.
Preparing your home with updates and deep cleaning helps you sell faster and for top dollar.
Pre-Market Timelines
"Let's talk about the timelines before listing a home with us."
Smart marketing and pro photos help your home reach the right buyers.
Clean, stage, and repair your home to boost value and attract buyers.
Home Valuation
"How do I know what my home is worth?."
Home value depends on size, condition, location, and how it compares to similar properties.
Buyers ultimately decide value—pricing must reflect market realities, not emotions.
What to Disclose
"What should you disclose when selling your home?"
Disclose known issues like leaks, pests, or repairs to stay legally safe
When unsure, disclose—honesty protects your sale.
Receiving Offers
"What happens after you get an offer on your home?"
A skilled negotiator helps you choose the best offer and terms.
Smart strategies can lead to stronger deals and faster closings.
Negotiations
"Why Sellers should never negotiate alone?"
Sellers should avoid talking directly to buyers—it can hurt the deal.
Skilled agents use strategy to protect your money and outcome.
Zestimate
"Zillow is an Algorithm"
Zillow guesses your home’s value without seeing it.
A local expert gives a more accurate, personalized price.
INSPECTIONS
"Should you get a home inspection before listing?"
Pre-listing inspections reveal hidden issues early and prevent costly surprises.
Knowing your home's condition gives you pricing power and peace of mind.
CONTINGENCIES
"Understanding contingencies in Real Estate contract"
Contingencies are contract conditions that must be met to close the sale.
Sellers should understand them to avoid delays or losing the deal.
WANT TO GET A FREE CUSTOM MARKET PROPOSAL?
Go to the next page to request a custom market proposal for your specific home
Lets Get You Prepared To Sell A Home
Community Videos
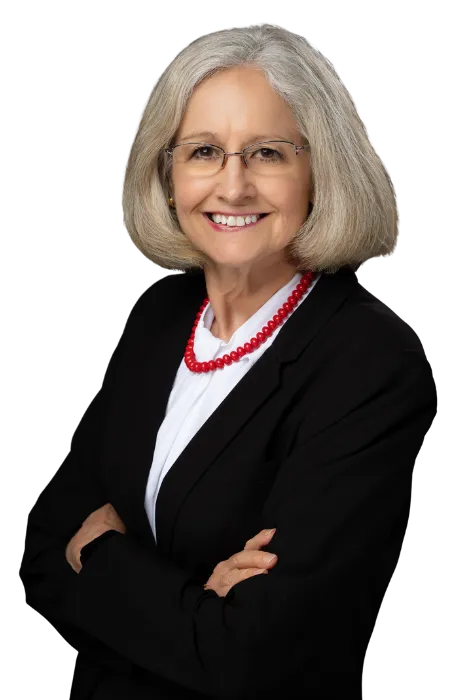
MEET LESA
We help you throughout the entire selling & buying process!
Lesa Miller | Realtor Lic# RB14023899
Lesa Miller is a highly respected and knowledgeable real estate professional with over two decades of experience in the Bloomington, Indiana area.
Known for her hands-on approach, she prioritizes clear communication, dedication, and transparency to guide her clients through every step of the buying and selling process.
As a top-producing RE/MAX agent, she has earned prestigious accolades, including the RE/MAX Platinum Level and the RE/MAX Hall of Fame award, recognizing her outstanding sales achievements and commitment to excellence.
With a background in business and law, Lesa has the expertise to navigate even the most complex transactions with confidence and skill.
Let's Get You Prepared To Sell Your Home
SUPPORT OUR SMALL BUSINESSES
Top 5 Things To Do In Brentwood
Top Tacos in Brentwood
41 Sand Creek Rd C, Brentwood
335 Oak St, Brentwood
Visit our blogs for more real estate tips, home tips, and local information!
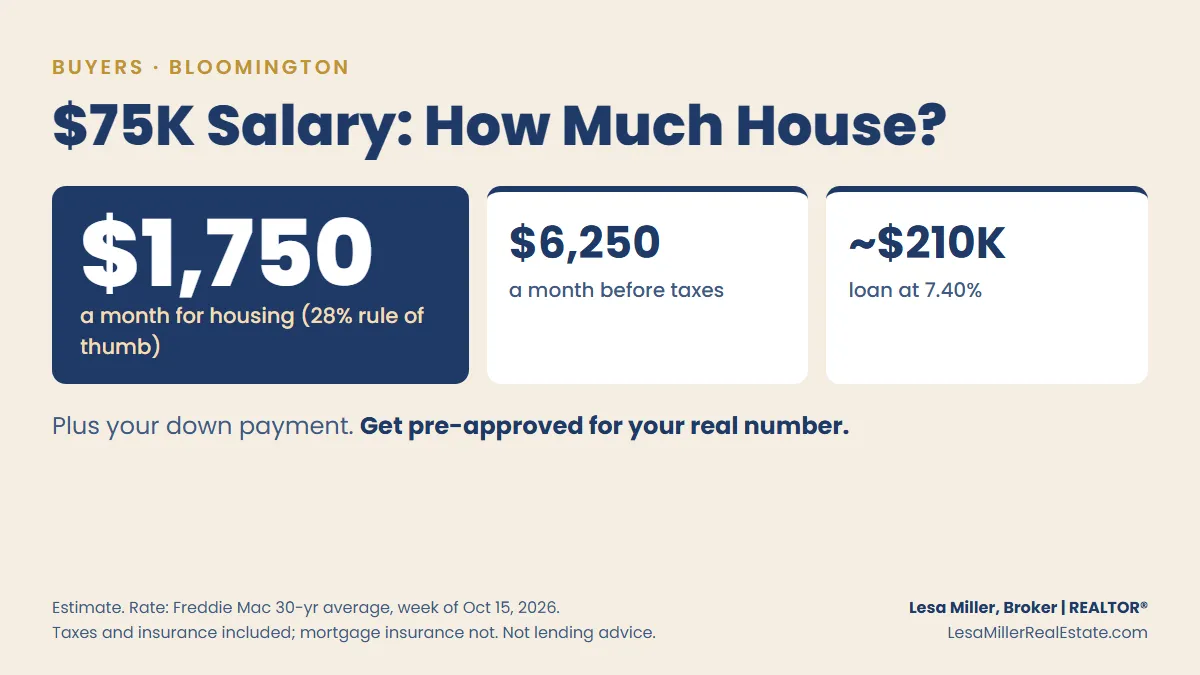
How Much House Can You Afford on a $75,000 Salary in Bloomington?
On a $75,000 salary, a common rule of thumb puts your monthly housing budget at about $1,750. At this week's national average rate of 7.40% for a 30-year fixed loan, that budget supports a loan of roughly $210,000, before mortgage insurance. Your down payment goes on top of that. Your own number depends on your debts, your credit and the lender, so treat this as a starting point, not an approval.
Lesa Miller is a REALTOR® and broker in Bloomington, Indiana, who helps first-time and relocating buyers in Bloomington, Ellettsville, Bedford and the surrounding towns. Here's the math I'd walk you through at the kitchen table.
Where does the $1,750 come from?
A $75,000 salary is $6,250 a month before taxes. A common guideline, often called the 28/36 rule, says to keep your housing payment at or under 28% of your gross monthly income. That's $1,750. The housing payment includes principal, interest, property taxes and homeowner's insurance.
It's a rule of thumb, not a law. Some loan programs approve higher ratios, and being approved for more doesn't mean more is comfortable for you.
What does $1,750 a month buy at 7.40%?
Here's an example. It is an estimate, not a quote.
Rate: 7.40%, Freddie Mac's 30-year fixed average for the week of October 15, 2026.
Property taxes: Indiana caps homestead property taxes at 1% of the home's gross assessed value, so I used 1% of the price as a high-side estimate. Many homes pay less, and voter-approved referendums can add to it.
Insurance: I set aside $100 a month as a placeholder. Get a real quote.
With 10% down, that works out to a price of about $233,000: a loan of about $210,000, around $1,455 a month in principal and interest, about $195 a month in taxes and $100 for insurance. With 5% down, it's closer to $222,000.
Under 20% down, most loans add mortgage insurance, which lowers the price a little more. A lender can give you the real figure.
What changes the number?
Your other debts. Car loans, student loans and credit cards count. The "36" in the 28/36 rule means total debt payments at or under 36% of gross income.
The rate. A lower rate stretches the same budget further.
A second income or a bigger down payment.
HOA fees. They come out of the same monthly budget.
My post on What Are Mortgage Rates in Indiana This Week? walks through how the rate moves your payment.
What should you do first?
Talk to a lender and get pre-approved. A pre-approval reads your actual credit, income and debts, so it replaces this estimate with a real number. Pre-Qualified vs. Pre-Approved explains the difference, and the cost of living in Bloomington covers the rest of the monthly picture.
Frequently asked questions
How much house can I afford on $75,000 a year?
Using the 28% guideline, about $1,750 a month for housing. At a 7.40% rate with 10% down, that's roughly a $233,000 price, before mortgage insurance. Your lender's pre-approval gives the real number.
Do property taxes in Indiana have a cap?
Yes. Indiana caps homestead property taxes at 1% of the home's gross assessed value. You need the homestead deduction on file to get the 1% cap.
Is the 28% rule required by lenders?
No. It's a common guideline. Lenders use their own standards, and some loan programs allow higher ratios.
Thinking about buying? Call or text (812) 360-3863, or visit LesaMillerRealEstate.com/Links. Let's start with what fits your budget.
This post is general information, not lending or financial advice. Talk to a lender about your situation.
WHAT PEOPLE ARE SAYING ABOUT
LESA MILLER
"LESA MILLER Is The Way To Go For A Successful Home Sale."
"Our first ever home sale. Lesa and her team made the experience so smooth. From our first meeting to the last it was all about us and how they made it an enjoyable experience. They were all unbelievably attentive and responsive to our needs.
- Jerry & Liqin A.
"The Strategy, Marketing And Pricing On The House Were Spot On."
"My father in law passed and we needed to sell his house. We met with three different agents and we quickly decided to go with Lesa. Lesa and her team are very knowledgeable, energetic and at the top of their game. Everything was spot on."
- Shaun & Heather B.
“Lesa Went Above and Beyond—Making a Difficult Sale Feel Easy”
"Lesa and her team were excellent. We bought a home while on vacation. We relied on her staff to not only view the house but she positioned us so well, that we followed her advice and we got the house for the price we wanted. Thank you!
- jilldenise12
Want to be sure you don't miss out on any local tips & local real estate market updates?
Have them delivered to your inbox.
Subscribe to the monthly digital newsletter below!


